AI CREDIT SCORING FOR US LENDERS
The credit intelligence layer for the invisible economy.
QuipuScore reads alternative data to approve the thin-file borrowers that bureaus cannot see. We built it where the signal is scarcest, and it is proven on more than 500,000 users in Latin America.
500K+
users scored
$12M+
USD disbursed to 50K+ clients
90%
thin-file or no-file borrowers
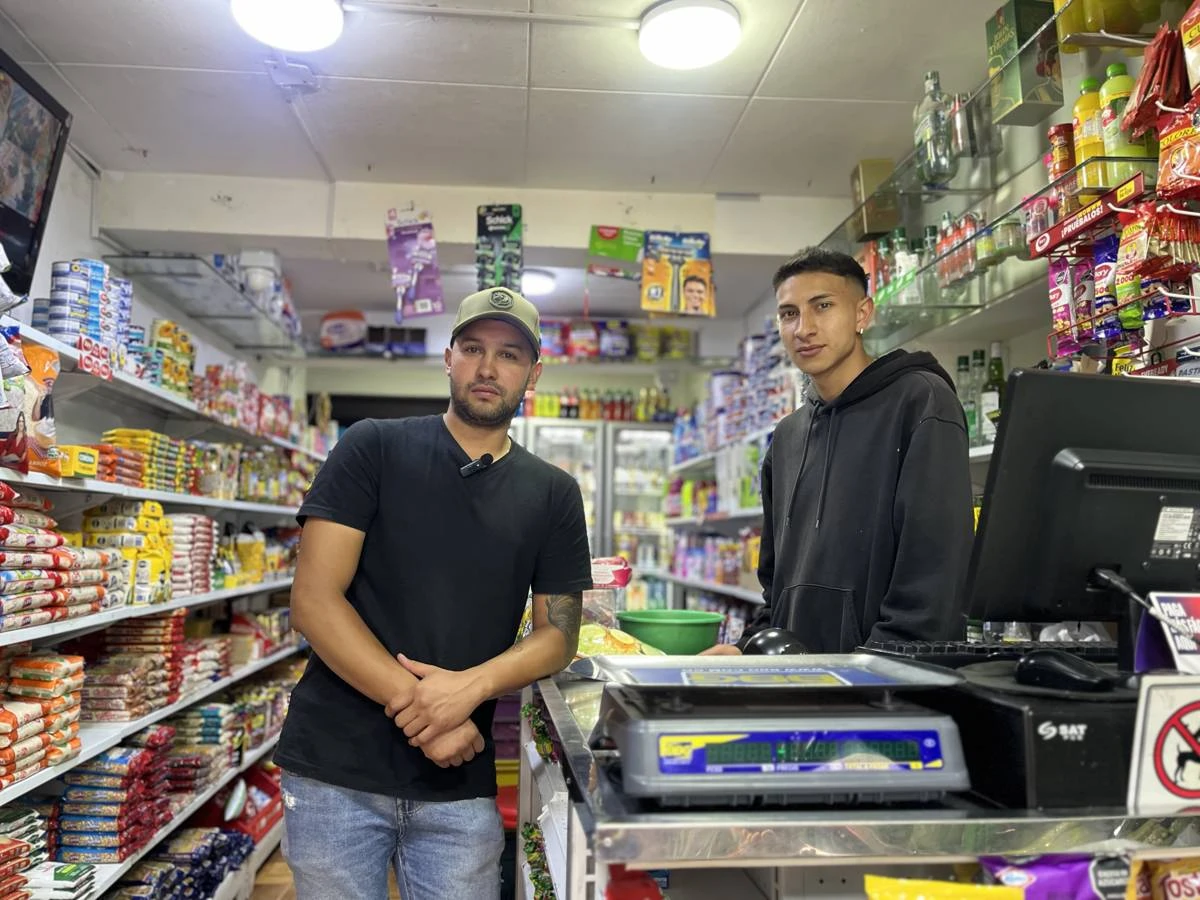
Informal micro-businesses in Colombia, where Quipu built its models.
THE US MARKET
This is no longer a niche problem.
Thin-file and gig-income consumers now sit at the center of US lending. They are no longer at its edge.
49M
Americans are credit invisible or unscorable.
Experian106M
cannot access fair credit rates.
Experian96%
of the unscorable could be scored today with alternative data.
Experian47.5%
of lenders cannot score 30% or more of their applicants.
Datos Insights, 202624.5%
of adults earn gig income.
Datos Insights, 202629.1%
used buy now, pay later in the past 12 months. That is leverage the bureau does not see.
Datos Insights, 2026Lenders lose twice.
They reject good borrowers they cannot see.
Thin-file and no-file applicants are declined automatically, including invisible primes who would have repaid. That revenue goes to competitors or to predatory lenders.
They absorb defaults priced on a stale snapshot.
A one-time bureau pull says nothing about what happens after disbursement. Thin files default about 5 percentage points more under traditional scoring. They are not riskier. They are unseen.
$6–7B
in annual lending left on the table
$4.4T
Latino market ceded to predatory lenders
The cost of standing still. CDFIs, credit unions and immigrant-serving fintechs leave this on the table because they cannot score the thin files in front of them. QuipuScore turns unscorable into bankable.
OUR APPROACH
The fourth dimension is real-time capacity to pay.
The bureau tells you how someone paid. Cash flow tells you whether they can pay, today and next month.
Solutions
The data exists. The intelligence is what is missing.
QuipuScore is the AI engine between your data sources and your credit decision. It connects to the data you can already access and returns a score you can explain.
Data sources
• Bank cash flow and transactions
• Utility, rent and telco payments
• Device and digital footprint
• Business photos, video and social presence
Quipu AI engine
QuipuScore• Models that work with any consented data source
• 400+ variables per user
• A score in under 10 seconds
• Explainable AI on every decision
Outputs for the lender
• Probability of default
• Repayment capacity
• Early-warning and opportunity alerts
• Reason codes for every decision
Built to be explained
Every Quipu score comes with its reasons, which gives you a head start on adverse-action and fair-lending requirements.
Reason codes on every decision
Your risk and compliance teams see what drove each score.
Fairness by design
Scores are built from behavioral signals and designed to remove gender, racial and origin bias.
Score from the first click
Evaluate risk from the moment a user downloads your app, with no credit history required.
Consent-based data
Connects to any data source you can access. You do not depend on a single provider.
Also available: Digital onboarding with no paperwork • Banking app for underbanked users • Smart collections • AI financial coach built on OpenAI
PROOF
Real scale, not a pilot.
Our models are trained and tested on real money, deployed to real clients and measured in repayment.
500K+
users scored in Colombia
Well past the threshold of statistical significance.
$12M+
USD disbursed
Money deployed and in repayment, observed and not projected.
50K+
real credit clients
Every prediction meets real repayment behavior.
90%
thin-file or no-file
Exactly the population traditional models reject.
AUC of 0.78 to 0.83 depending on the data source. We lend on our own models, so every score is tested against real repayment and the models keep learning.
40%
Better than the inclusion scores of bureaus like Experian. We beat the benchmark built for this population, not the generic score.
Quipu internal benchmark.
More approvals at the same risk
Approve more of the applicants you decline today without moving your loss rate.
The same volume with fewer defaults
Keep approvals flat and cut expected loss on the portfolio you already originate.
You choose which side of the lift to capture.
We solved the hardest case first.
US lenders are only starting to use transaction data for thin-file consumers who already have a bureau file. We built alternative scoring where the bureau barely exists. A market with mature data infrastructure is an easier problem.
Latin America's informal economy
• Minimal bureau coverage
• Cash income and informal jobs
• Sparse, noisy digital signal
US thin-file consumers
• Mature data infrastructure
• Broad bank-account and digital-payment coverage
• Richer consumer-permissioned data
• Colombia's largest neobank: 27M users, active proof of concept | • Digital wallets: Embedded scoring and monitoring | • Traditional microfinance institutions: Field-based lenders
One model works for a 27M-user neobank and a traditional microfinance lender. The edge is the methodology, not a lucky use case.
Featured in: Forbes Colombia (in Spanish) • Global Finance • TED talk by our CEO, Mercedes Bidart
WHO WE SERVE
Built for lenders that already see thin files.
Our first US partners have thin-file applicants in front of them every day and no good way to score them.
CDFIs
Mission-driven lenders serving thin-file borrowers daily, under pressure to grow responsibly.
Credit unions
Member-owned and rooted in their communities, looking to serve gig-income and immigrant members without adding risk.
Immigrant-serving fintechs and neobanks
Fast-growing Latino customer bases they can onboard but cannot yet underwrite.
Scoring as a service, by API
Priced per query or as a revenue share. Your credit, risk or lending lead decides. We do not lend in the US. We power the lenders who do.
Quipu scores from zero.
No home-country bureau file is required. We use the data the applicant already generates in the US.
TEAM AND BACKERS
Born at MIT. Learned in Latin America. Now building for the US.
Quipu began as an incubation at MIT DesignX and has grown by lending to people the traditional system left out.
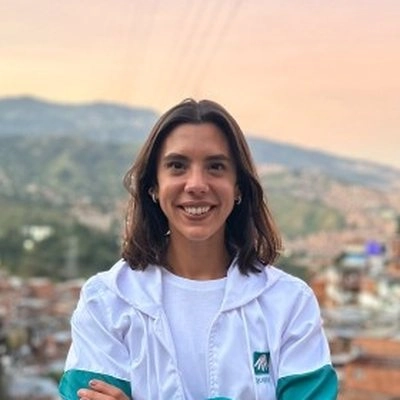
Mercedes Bidart
Co-founder and CEOMIT graduate and MIT Technology Review Innovator Under 35 (2025).
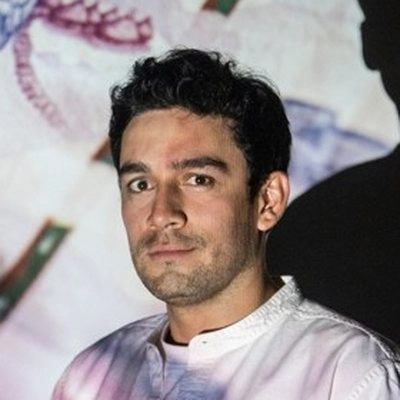
Juan Constaín
Co-founder and CPOFormer VP of Credit at Davivienda and Head of Strategy at Finaktiva.
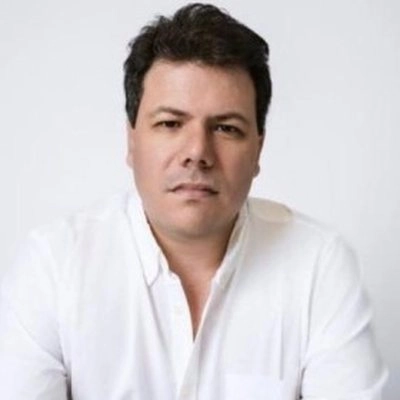
Eduardo Carrasquilla
Co-founder and CTO10+ years engineering financial architecture and scalable systems across LatAm.
Backed by global impact and venture investors
IDB Lab, Impacta.vc, Decelera Ventures, G2 Momentum Capital, Kiva, Roots of Impact and data.org, among others.
LET'S TALK
How many creditworthy borrowers are you turning away?
Let us help you see who your current model is leaving out. In a 30-minute conversation we will review how you underwrite today, where thin-file applicants drop out, and how QuipuScore could fit your data and your credit policy.
Social
Contact
[email protected]
Bogotá, Colombia
Privacy policy
Market statistics: Experian and the Datos Insights 2026 lender survey. Performance figures reflect Quipu's operations in Colombia. Quipu provides scoring and analytics to lenders and does not lend in the US.
© 2026 Quipu Score. All rights reserved.